01
Talk About Your Goals
Discuss your timeline, priorities, budget considerations, and what you're looking for in a home.
Buying your first home can feel like a lot at once:
How much can you afford? How much will you need upfront?
Which loan makes sense? What happens after you find a house you like?
You don't need to figure it all out on your own.
This first-time homebuyer guide explains what to expect when buying a home in Springfield and Southwest Missouri, from preparing your finances and exploring mortgage options to searching for a home, making an offer, completing inspections, and closing.
Graddy Real Estate works with buyers at different stages of the process, whether you're ready to start touring homes or still a year or two away.
Your Buyer Roadmap
Graddy Real Estate's buyer process starts with understanding your goals rather than immediately sending you listings. The details can vary based on the home, financing, and purchase contract, but knowing the roadmap makes it easier to understand what comes next.
Discuss your timeline, priorities, budget considerations, and what you're looking for in a home.
Get preapproved and establish a realistic price range and monthly payment with a lender.
Review the buyer agreement, services, and compensation before beginning home tours together.
Receive a customized property search and explore homes that fit your priorities.
Review the property, offer strategy, negotiations, inspections, and contract deadlines.
Work through financing, title, insurance, final documents, and the steps required before you receive possession.
The details can vary based on the home, financing, and purchase contract, but knowing the roadmap makes it easier to understand what comes next.
Being ready to buy isn't only about qualifying for a mortgage.
Consider your income, debts, credit, savings, expected monthly housing costs, and whether you're prepared for maintenance and other homeownership expenses.
You should also think about your timeline. If you may move again soon or need more financial flexibility, continuing to rent may make more sense for now.
Gather information about your income, employment, savings, debts, and monthly expenses.
Think about the monthly payment you would feel comfortable carrying while still leaving room for emergencies, repairs, savings, and your other financial goals.
A lender can help determine what financing you may qualify for. That doesn't mean you have to spend the maximum amount you're approved to borrow.
That's still a good time to prepare.
You can work on your credit, build savings, learn about mortgage options, explore different parts of the Springfield area, and watch homes within your potential price range.
Graddy Real Estate can also set up a customized property search so you can follow the market while you prepare instead of starting from scratch when you're ready.
Plan for the Full Cost
You do not necessarily need a 20% down payment to buy a home. The amount you'll need depends on your mortgage, the property, transaction costs, and your individual circumstances.
| Homebuying Cost | What It Means for a Buyer |
|---|---|
| Down payment | The portion of the purchase price you pay rather than finance |
| Closing costs | Mortgage, title, settlement, and other transaction expenses |
| Earnest money | A deposit handled according to your purchase contract |
| Inspections | Cost of evaluating the home's condition |
| Appraisal | Property valuation commonly required for mortgage financing |
| Prepaid expenses | Certain taxes, insurance, or escrow amounts that may be due |
| Moving and repairs | Costs that can arise before and after you move in |
Some expenses may be negotiable or eligible for assistance, depending on the transaction and financing.
Two homes with the same price can have different monthly costs.
Depending on the property and financing, your housing expenses may include principal and interest, property taxes, homeowners insurance, mortgage insurance, HOA dues, utilities, and maintenance.
Ask your lender to show you both the estimated monthly payment and estimated cash to close for the financing you're considering.
Step Two · Explore Financing
First-time buyers may have several mortgage options. Which one fits depends on your financial qualifications, the property, and program requirements.
Common options include conventional, FHA, VA, and USDA financing.
Instead of choosing based only on the advertised interest rate or down payment, ask lenders to help you compare:
Missouri Homebuyer Resources
Yes. The Missouri Housing Development Commission (MHDC) offers homebuyer programs that may help eligible buyers with financing and upfront costs.
Its First Place program serves qualified first-time homebuyers and veterans, while Next Step may also be available to eligible repeat buyers. Program limits, rates, assistance, and other requirements can change.
A participating lender can help determine whether you qualify.
Explore MHDC Homebuyer ProgramsUnderstanding Your Mortgage
Prequalification is generally an initial estimate based on financial information you provide.
Preapproval typically involves a more detailed lender review.
Neither is a final loan approval.
When you're comparing lenders, the Consumer Financial Protection Bureau's mortgage resources can also help you understand and compare Loan Estimates.
Learn How to Compare Loan EstimatesStep Three · Understand Buyer Representation
A buyer's agent can help you search for properties, evaluate market information, arrange showings, prepare offers, negotiate terms, and coordinate the transaction after an offer is accepted.
Understanding the Agreement
A written buyer agreement establishes the services your real estate professional will provide, the terms of the relationship, and how compensation will be handled.
If you're working with a real estate professional who is subject to current written-agreement requirements, you'll generally enter into an agreement before touring a home together.
Simply attending an open house independently does not by itself require you to sign a buyer agreement.
Buyer-agent compensation is negotiable and is not set by law. Read the agreement and ask questions about services, duration, compensation, and any amount you could be responsible for paying before signing.
Graddy Real Estate
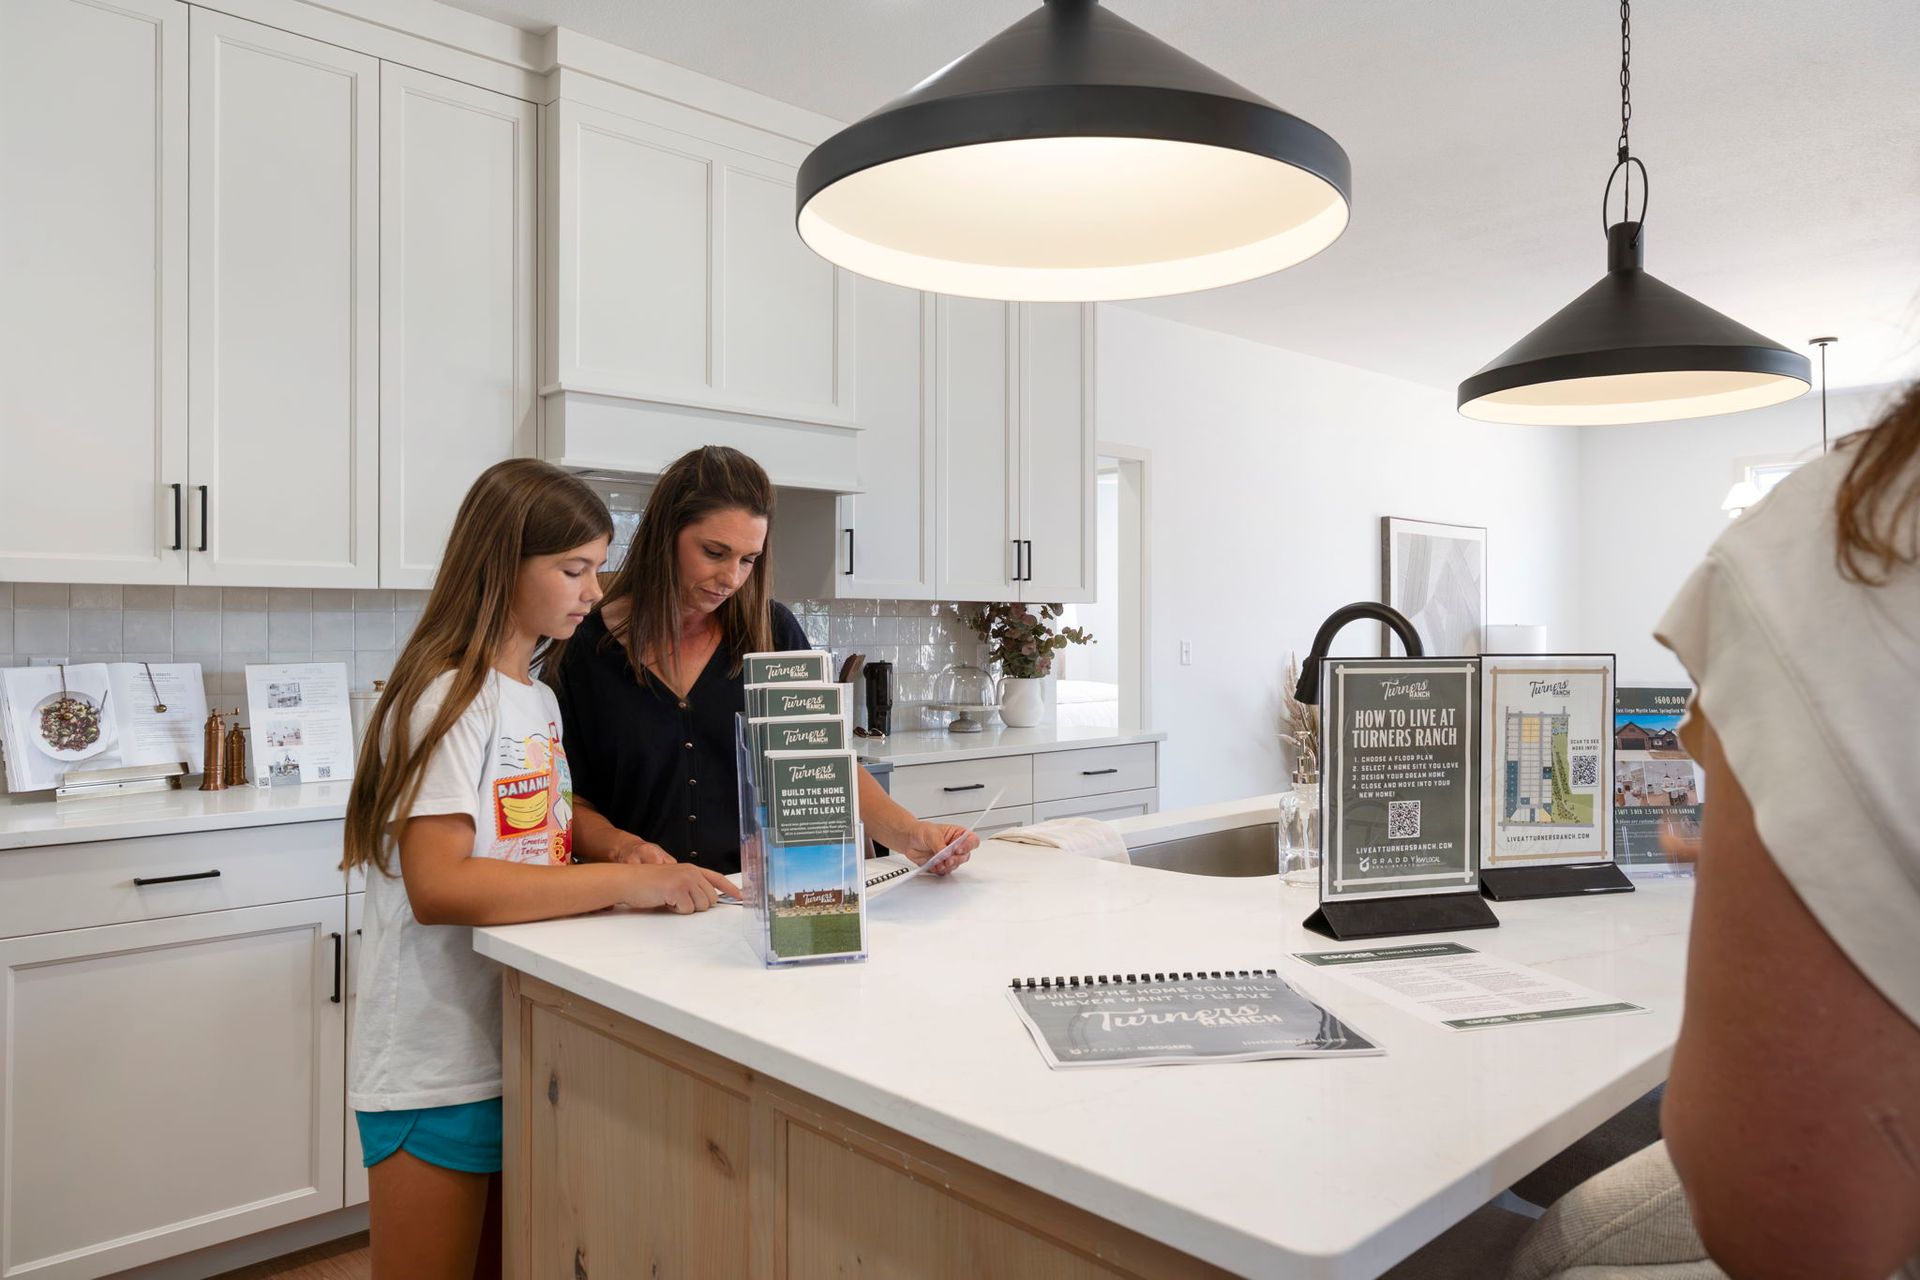
Graddy Real Estate uses a team-based approach to help buyers throughout Springfield and Southwest Missouri.
Kari Wyrsch serves as Graddy Real Estate's lead Buyer's Agent and is supported by showing partners.
Depending on where you are in the process, the team can help with the steps outlined below.
From Your First Conversation to Closing
Step Four · Start Your Home Search
Start with the factors that affect your everyday life and long-term ownership—not just the features that look good in listing photos.
Consider your budget, location, commute, property condition, maintenance needs, utilities, and the type of home and setting you prefer.
Springfield and nearby communities such as Nixa, Ozark, Republic, Battlefield, and Rogersville offer different property types and settings.
Instead of relying on broad descriptions of which area is "best," compare locations based on your priorities and the homes actually available within your budget.
Explore Springfield & Surrounding CommunitiesLook Beyond the Listing Photos
Look beyond finishes and furniture.
For rural and semi-rural properties, also determine whether the property uses public utilities or systems such as a private well or septic system, where applicable.
A showing helps you decide whether to continue evaluating a property. It does not replace a professional home inspection.
Beyond Public Listings
Yes.
When appropriate for a buyer's search, Graddy Real Estate also uses strategies beyond publicly listed properties.
The team's home-search strategies can include direct homeowner outreach, local agent networks, targeted campaigns, and outreach through Graddy's existing contacts.
Off-market opportunities aren't guaranteed, but these strategies can expand the search when publicly available listings aren't producing the right fit.
Start Your Home SearchAn offer is more than the price you're willing to pay.
Depending on the transaction, the purchase agreement may address financing, earnest money, inspection provisions, appraisal considerations, closing, possession, and other negotiated terms.
Your agent can help you review relevant property and market information and understand the proposed terms before you sign.
Earnest money is a deposit handled according to the purchase contract.
The amount, deadline, how it is held, and circumstances under which it may be returned or forfeited depend on the agreement.
Contract provisions related to financing, inspections, appraisal, or other conditions can affect your rights and obligations if something changes during the transaction.
Waiving or modifying protections can increase risk.
Your real estate professional can explain the transaction process. For legal advice or questions about your rights under a contract, consult a qualified attorney.
A home inspection and appraisal serve different purposes.
A home inspection evaluates visible and accessible aspects of the property's condition within the inspector's scope of work.
An appraisal provides an opinion of value for the lender or another intended purpose.
An acceptable appraisal does not mean a home has no defects, and an inspection does not determine the property's value for your lender.
First determine what was found, whether further evaluation is appropriate, and how the issue could affect safety, maintenance, or repair costs.
Your options depend on the purchase contract and circumstances. They may include proceeding, negotiating, requesting repairs, or exercising rights available under the agreement.
There is no universal rule that every inspection issue gives a buyer an unrestricted right to cancel.
STEP EIGHT · UNDER CONTRACT TO CLOSING
Once you're under contract, several pieces of the transaction move forward at the same time.
While You're Under Contract
Depending on your purchase and financing, that may include:
Important: Stay responsive to your lender and transaction professionals, and ask before making significant financial changes while your mortgage is being finalized.
For most mortgages covered by federal disclosure requirements, you'll receive a Closing Disclosure at least three business days before closing.
Use that time to compare the final loan information with your most recent Loan Estimate and ask about anything you don't understand.
If you're instructed to wire closing funds, independently verify the instructions with your closing provider using a trusted phone number.
Do not rely solely on wiring information contained in an unexpected email.
Possession depends on the purchase contract and completion of the required closing steps.
Confirm the timing before scheduling movers, deliveries, or other move-in arrangements.
YOUR HOMEBUYING ROADMAP
From preparing your finances to getting ready for closing, use this checklist to keep track of important tasks throughout your homebuying journey.
YOUR FREE HOMEBUYING RESOURCE
Want a homebuying resource you can save and refer to as you prepare?
Get Graddy Real Estate's guide to the buyer process, Springfield neighborhood snapshots, preparing to buy later, off-market home searches, FAQs, and planning tools.
Includes neighborhood data from SOMO FlexMLS, January 1–October 15, 2026.
HELPFUL ANSWERS · BEFORE YOU BUY
There isn't one amount that applies to every buyer.
Your cash needs can include the down payment, closing costs, inspections, prepaid expenses, moving costs, and reserves for repairs or emergencies.
Your lender can provide an estimated cash-to-close amount for the financing you're considering.
Yes. Some mortgage programs allow qualified buyers to purchase with less than 20% down.
Mortgage insurance, eligibility requirements, or other costs may apply.
Yes. The Missouri Housing Development Commission offers homebuyer programs that may assist eligible buyers.
MHDC's First Place program serves qualified first-time homebuyers and veterans, while Next Step may also be available to eligible repeat buyers.
Eligibility, assistance, rates, and program requirements can change, so confirm current information with MHDC and a participating lender.
There is no single credit score requirement for every mortgage.
Requirements vary by lender, loan program, and other aspects of your financial profile.
You can start preparing now by reviewing your credit, building savings, learning about financing, exploring neighborhoods, and watching homes within your potential budget.
Graddy Real Estate can also set up a customized search so you can learn the market while you prepare.
Buyer-agent compensation is negotiable and should be addressed in your written agreement.
Depending on the transaction, buyers may also negotiate for compensation to be provided by the seller or another permitted source.
Make sure you understand any amount you could be responsible for before signing your agreement.
YOUR NEXT STEP · WHEN YOU'RE READY
Whether you're ready to start looking at homes or still figuring out what comes next, you don't have to have everything worked out before reaching out.
Graddy Real Estate's buyer team can help you understand your next steps, prepare for your home search, and move forward at a pace that makes sense for you.
We are the number one stop in the region for buying and selling luxury real estate. We’ve been serving the area for more than 40 years, and we do it with pride.
619 S Florida Ave
Joplin, MO 64801
Office:
(417) 893-0891
© 2026 Graddy Real Estate Keller Williams Local Each office is independently owned and operated. An SC Marketing Technologies Website